
Nifty Analysis for Next Week starts with a rare and uncomfortable fact. Nifty has closed eight consecutive weekly candles in red, the first time this has happened since 2001.
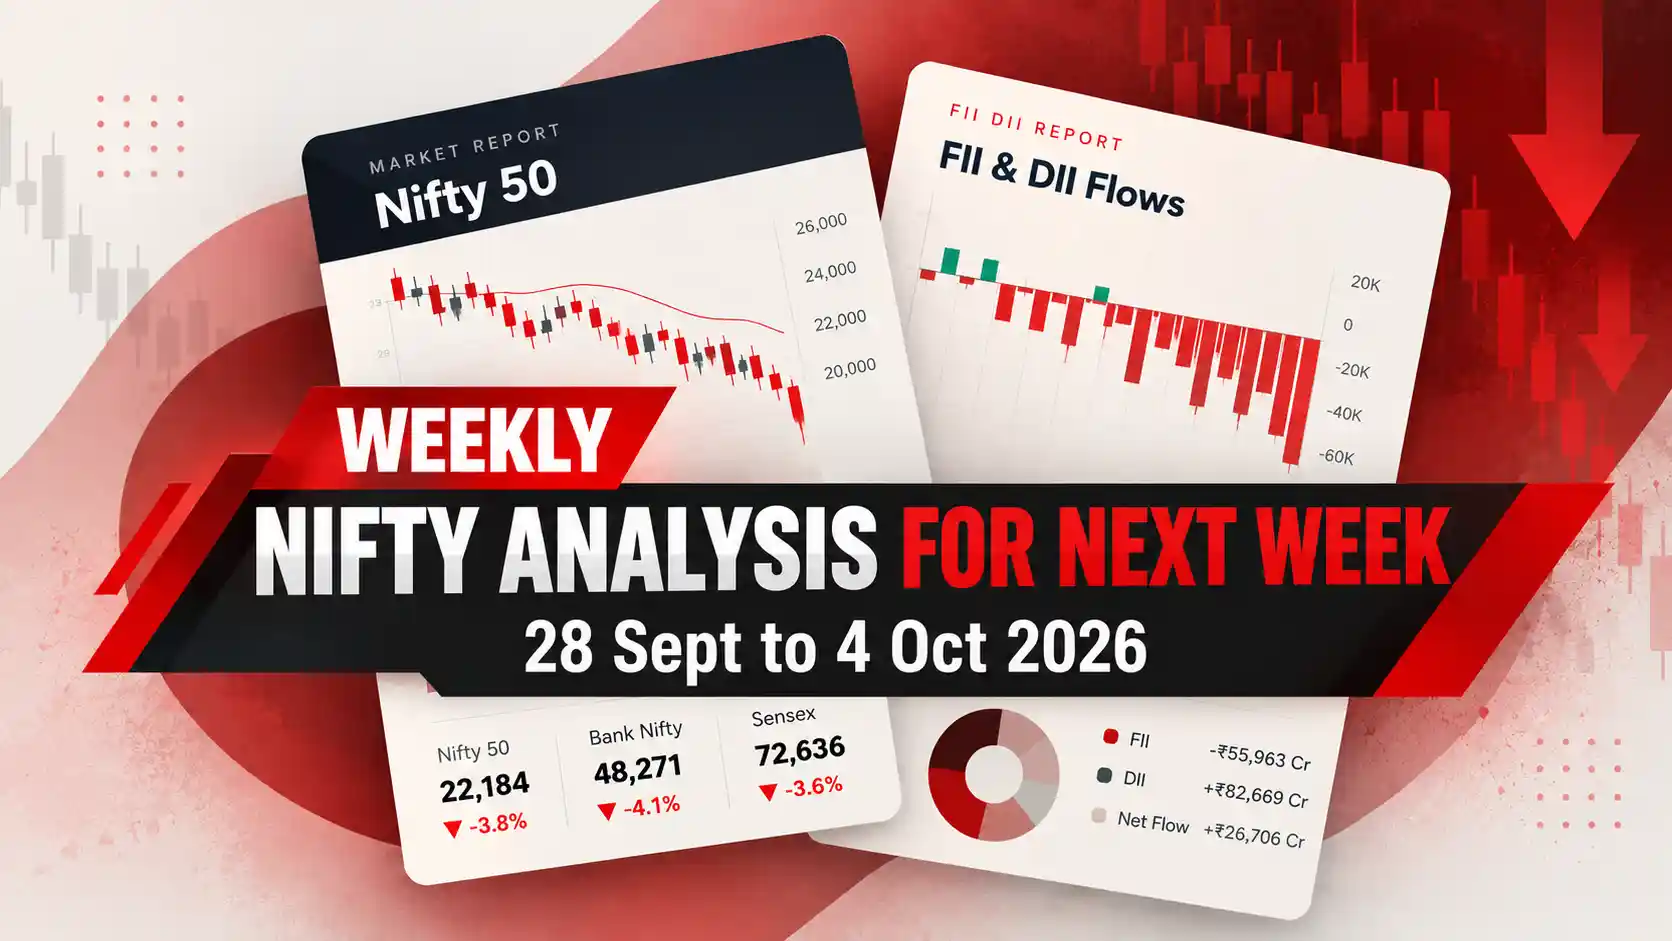
The index fell 3.11% to 22,421.95 this week, and FIIs sold ₹34,966.07 crore in the cash market in just four sessions. Friday 2 October was a market holiday for Gandhi Jayanti.
Our market view is simple and confident. This is a risk off, liquidity driven market where foreign money is leaving because US yields are high and the rupee is weak. A pullback can come, but it is not a clean buying signal yet.
KEY TAKEAWAYS:
1. FIIs sold ₹34,966 crore while DIIs bought ₹33,455 crore, so domestic money slowed the fall but did not stop it.
2. High US yields and a weak rupee are the main reasons foreign money is leaving India.
3. Only 99 stocks advanced against 397 declining in the Nifty 500 on Thursday, so the weakness is broad and not limited to a few sectors.
4. IT was the only sector in green, which shows defensive rotation and not fresh risk appetite.
5. A bounce is likely, but the trend stays weak until buyers prove otherwise. Full support and resistance levels are broken down in the technical section below.
Nifty Analysis for Next Week: Why Nifty Fell 3.11%
Nifty opened the week at 23,064.90, made a high of 23,080.25 near the open, and hit a low of 22,217.30. It closed at 22,421.95, down 3.11% from last Friday's close.
Every session closed lower than the one before.
The trigger was crude oil. After the US rejected a proposal to open the Strait of Hormuz, Brent jumped about 4% to near $108 a barrel on Monday. India imports most of its oil, so costlier crude means a wider import bill, a weaker rupee and higher inflation risk. Markets price that chain very quickly.
That is why the damage was widest in rate and fuel sensitive pockets. The index did not fall further only because DIIs bought ₹33,455 crore, so domestic money is cushioning the market but not reversing it.
The implication for Nifty Analysis for Next Week is clear. The market is reacting to macro headlines first and company news second. Until crude stops dominating headlines, rallies will stay short and get sold into.
Nifty Analysis for Next Week: Bank Nifty Falls 2.03% but Holds Better Than the Index
Bank Nifty opened at 55,347.80, made its weekly high of 55,390.10 on Monday morning, and fell to a low of 53,785.70 on Tuesday. It closed at 54,450.75, down 2.03% from 55,580.40.
Bank Nifty lost less than Nifty's 3.11%. Financial Services fell only 1.60%, which tells us selling hit cyclical and consumption linked sectors harder than lenders.
The next big trigger is the RBI decision on 7 October. The market expects a move from 5.25% to 5.50%. A hike can support lending margins but raises bond market and credit risk, so banks can swing both ways around the event.
Bank Nifty matters for Nifty Analysis for Next Week because heavyweight lenders decide whether any Nifty bounce can last.
Nifty Analysis for Next Week: Top 3 Events That Shaped the Nifty View
FIIs sell ₹10,148 crore and ₹9,484 crore in back to back sessions
The two sessions wiped out over ₹9.5 lakh crore of investor wealth in a single day and pushed Nifty into an eighth red week. DIIs bought ₹11,271 crore and ₹10,041 crore in the same sessions, which kept the fall orderly. The next signal to watch is the first day FIIs stop selling.
US 10 year yield jumps to 5.34% and the 30 year to 5.62%
Yields at multi year highs forced a repricing of long duration assets like technology stocks and pulled money back toward US bonds. They cooled later in the week after Fed official Williams said there was no urgent need for more hikes, and October hike odds fell to 38%. Further yield relief is the cleanest trigger for an Indian market bounce.
US rejects Hormuz proposal and Brent spikes 4% to $108
The shock hit emerging market sentiment first. Brent later eased toward $99 on talk of a European strategic reserve release and hints of US sanctions relief for Iran. The market now needs crude to stay below $100 before oil sensitive sectors can recover.
Nifty Analysis for Next Week: Why FIIs Sold ₹34,966 Crore
The main reason Nifty is falling is FII selling. FIIs sold ₹34,966.07 crore this week, with the peak outflow of ₹10,148.41 crore on Wednesday. Behind this, US dollars are leaving Indian markets for four reasons.
First, higher US yields. The US 10 year yield touched about 5.34% and the 30 year reached 5.62%. When safe US assets pay this much, foreign funds ask why they should take emerging market risk.
Second, currency risk. The rupee is pinned near its historical support at ₹96 per dollar. A weak rupee cuts the dollar return on every Indian stock an FII owns, so even a flat market becomes a loss for them.
Third, better global opportunities. US markets and AI related assets are attracting capital. A dollar index near 101.13 and a strong US PMI of 58.4 keep the dollar in demand.
Fourth, macro pressure from crude oil, inflation and weak global risk appetite adds to the other three.
DIIs bought ₹33,455.30 crore, almost matching the FII outflow. That is why the index fell 3.11% and not more. But domestic buying is absorbing a flow, not changing its direction.
What to monitor: a pause in FII selling, cooling US yields and a rupee that stops sliding. Until FIIs turn buyers for at least two sessions, every bounce is a chance for institutions to sell.
Nifty Analysis for Next Week: Sector Rotation Shows Defensive Money
Sector data backs our risk off view. Auto fell 5.03%, Capital Markets 4.84% and Metal 4.46%, so the market is selling cyclicals and high beta stocks as FIIs pull money out and US yields stay high.
IT was the only sector in green at 0.34%, helped by a weak rupee, and Financial Services fell just 1.60%. That is defensive rotation, not fresh risk appetite. With 397 Nifty 500 stocks declining against 99 advancing, the weakness is broad.
For Nifty Analysis for Next Week, the first sign of a real recovery would be Auto and Capital Markets stabilizing. Until then, bounces stay sell on rise.
Nifty Analysis for Next Week: Call Writers in Control
Option data also backs our risk off view. The Nifty PCR is 0.68, so call writers dominate and do not expect a strong rally. The highest call OI at 23,000 caps upside, while the highest put OI at 22,000 is the floor writers will defend. Max Pain at 22,550 is close to spot, so there is no strong expiry pull in either direction.
India VIX at 14.45 is not a panic reading, so fear has not peaked. If the 22,000 put wall breaks, hedging demand can lift VIX fast and speed up the fall.
Bank Nifty is similar. The PCR is 0.86, resistance is at 58,000 and support at 54,000, with spot just above the put wall. Max Pain at 56,000 is far overhead, so call writers still hold the edge.
The message in Nifty Analysis for Next Week is capped upside, a defended floor and rising hedging risk below it. Track live figures on the NSE option chain. All data refers to the 06 October expiry.
Nifty Analysis for Next Week: Nifty Technical Analysis for Next Week Says Pullback, Not Buying Signal
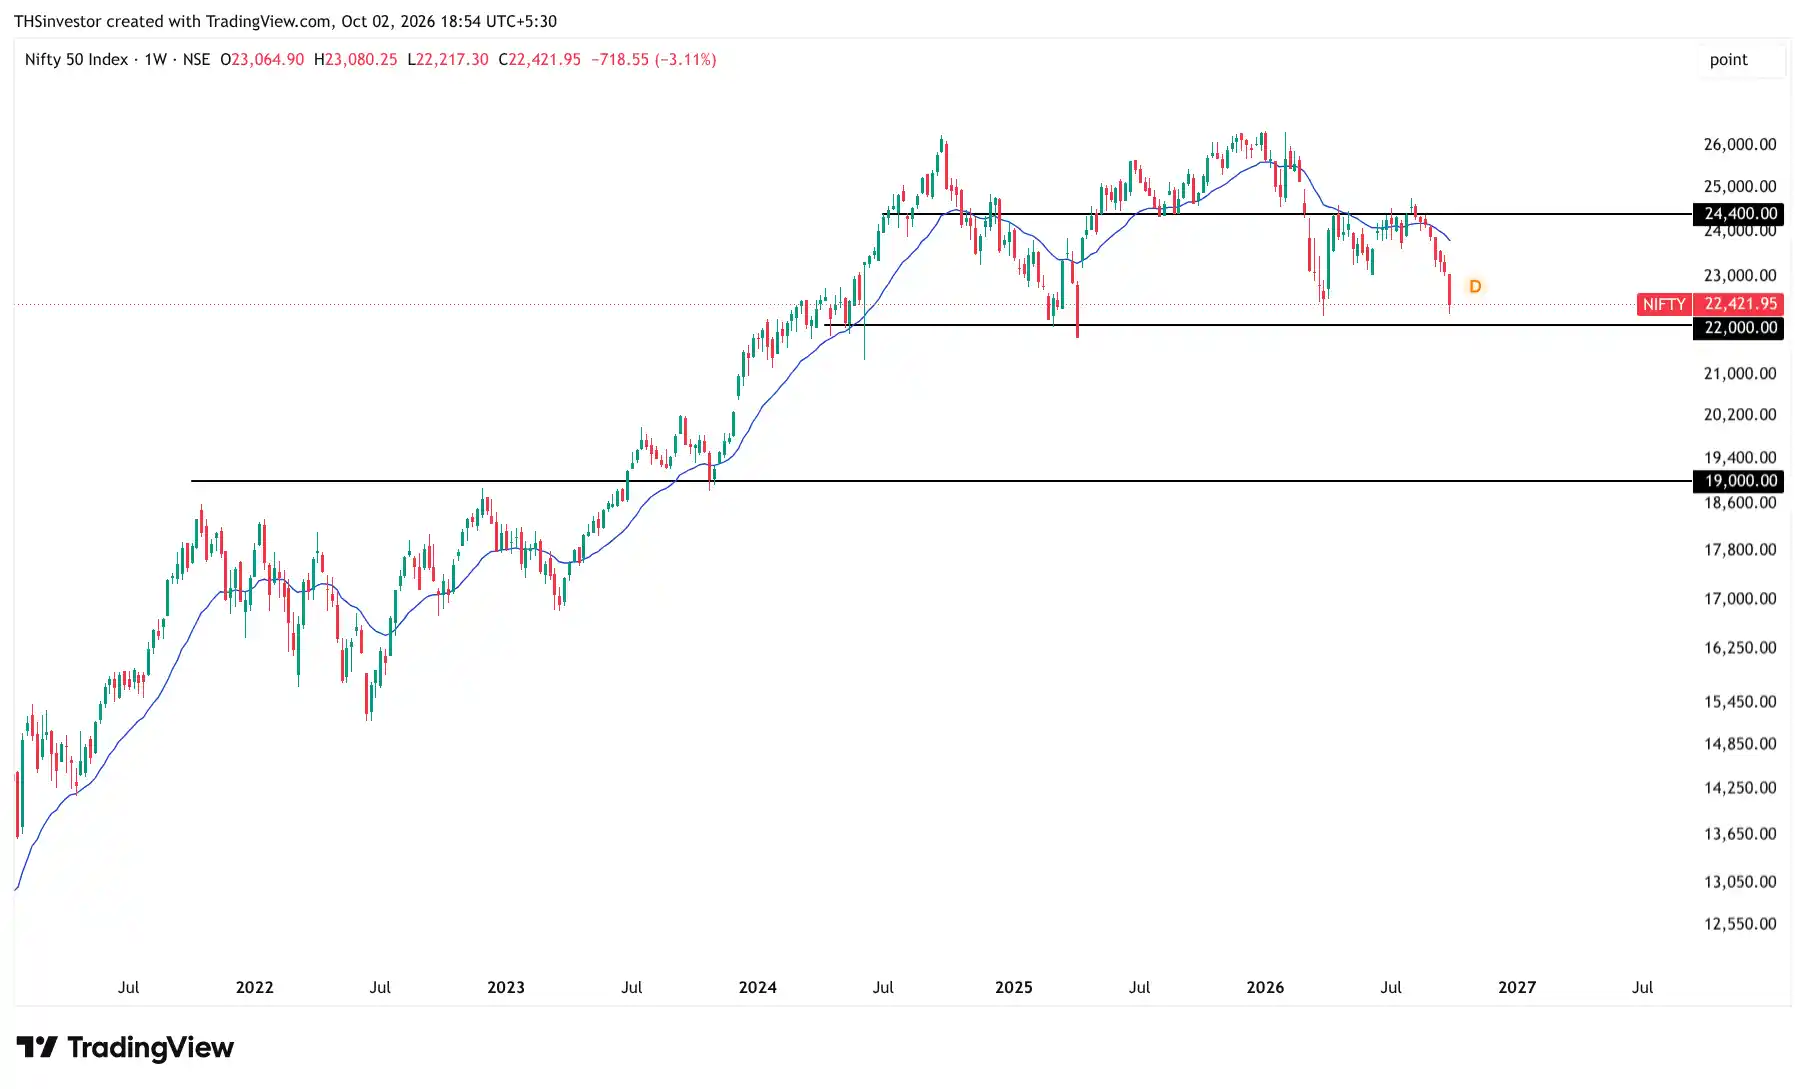
Key Resistance: 23000 is the first hurdle, where the 21 EMA sits. Nifty must close above it before any real recovery can begin. The next upside level is 24400.
Key Support: 22000 is the strong support zone, and this week's low of 22,217 came very close to it. If 22000 breaks decisively, there is no strong support until 19000.
Momentum: Weekly RSI has entered the oversold region, and the daily chart shows RSI divergence. A pullback is certainly on the cards. But oversold readings can last for weeks in a falling market, so a bounce is not a buying opportunity by itself.
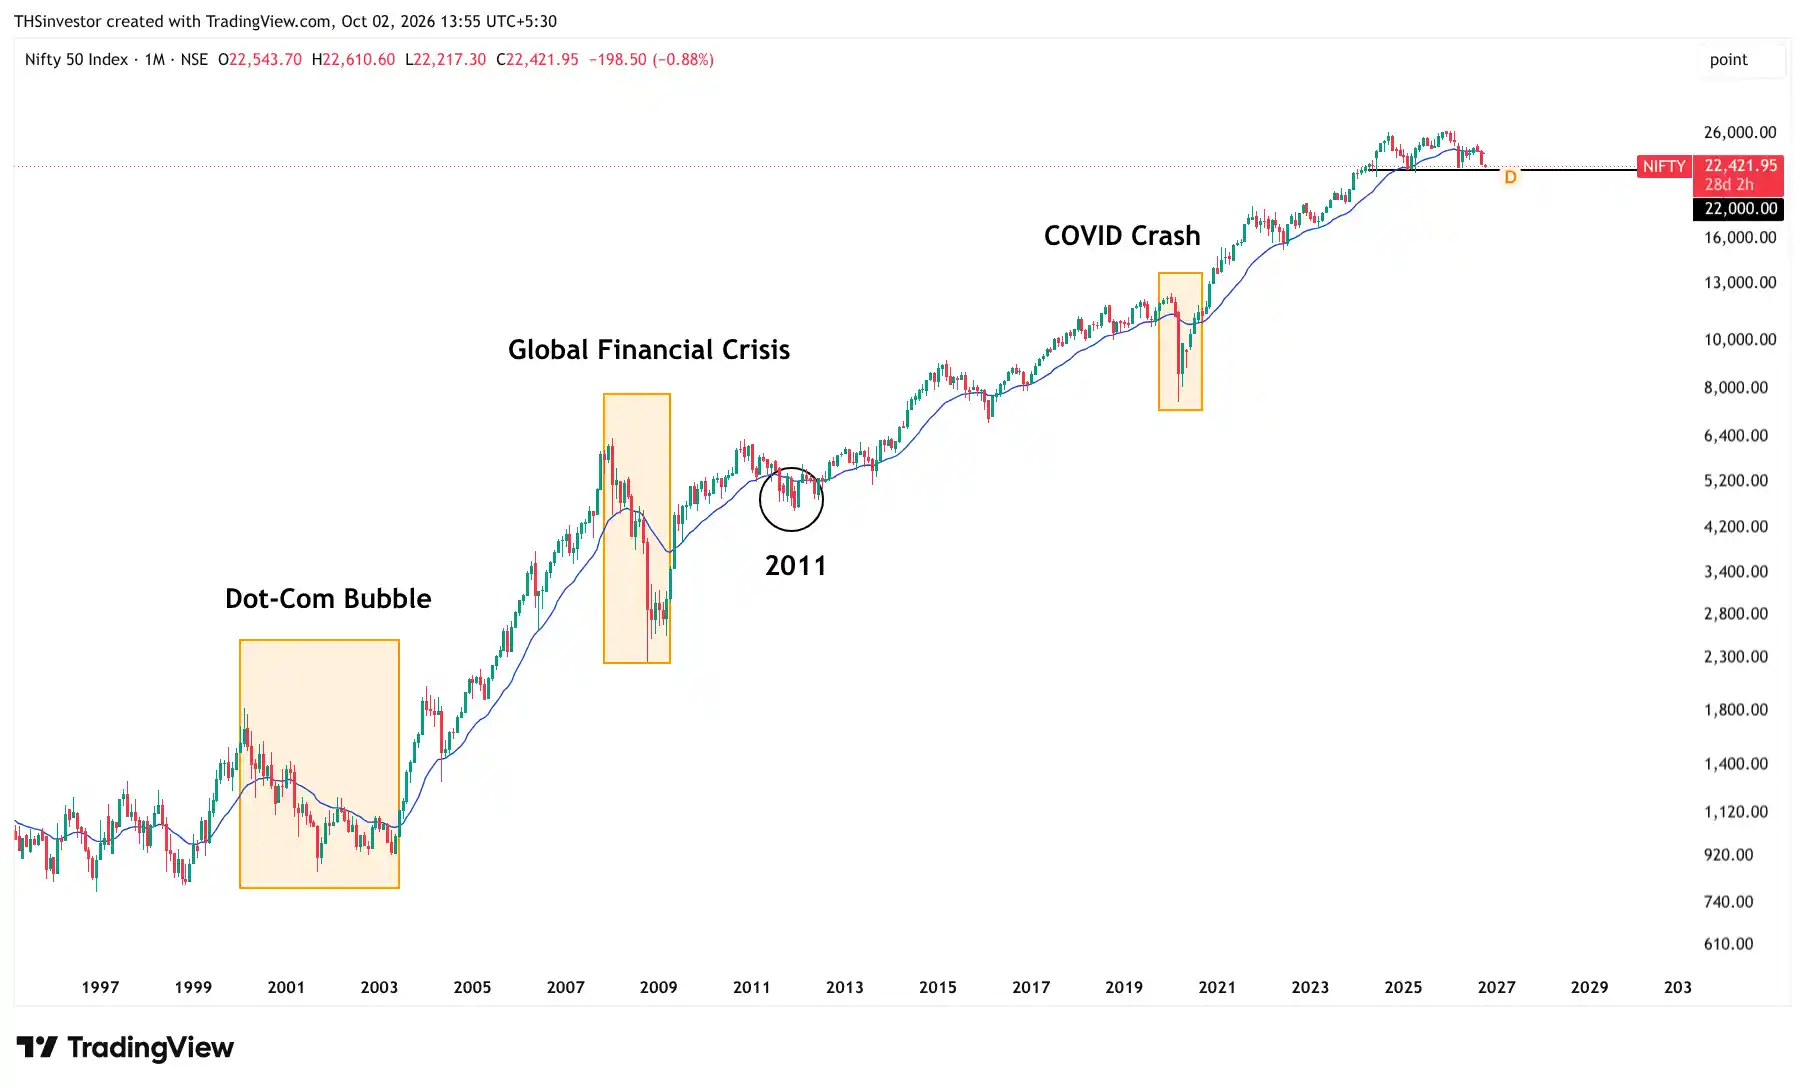
First, this could be a time correction. After the powerful one way rally post COVID, Nifty may simply be correcting through time without anything serious happening in the background.
Second, the 21 month EMA (blue line on the monthly chart) has historically been respected in normal corrections, except in 2011. Major breaks happened only in extreme events like the dot com crash, the Global Financial Crisis and COVID. This is a zone where long term investors find valuations attractive and buying interest rises, so a similar reaction could come soon.
Third, retail investors are getting frustrated with the market, and big players often use that as liquidity for the next bull run.
Bias: Sell on rise until 23000 is reclaimed. Do not treat the pullback as a buy on dip signal.
Invalidation: A daily close above 23000 is the first sign of recovery, and a close above 24400 flips this view. A decisive close below 22000 confirms a deeper correction toward 19000.
Nifty Analysis for Next Week: Most Likely, Bull and Bear Cases
The market view for Nifty Analysis for Next Week is risk off and liquidity driven. Foreign selling, high US yields and a weak rupee are repricing macro risk faster than domestic buying can absorb it. Our bias stays defensive, so bounces are chances to reduce risk, not to add it.
Next week has three macro triggers. The US ISM Non Manufacturing PMI comes on 5 October. The RBI rate decision comes on 7 October, with the market expecting a hike to 5.50% from 5.25%. The third is the direction of US yields and Brent crude.
Most likely case, about 50% probability: A volatile relief bounce. Oversold conditions and DII buying produce a pullback, but it fades near the resistance flagged in the technical section. FII selling slows but does not turn into buying. IT and Defence hold better, while Auto and Realty stay heavy.
Bull case, about 10% probability: Triggers are cooling US yields, Brent holding below $100, a steadier rupee and FIIs turning net buyers for at least two sessions. A close above the first resistance in the technical section would confirm it. Institutions would then cover shorts, and Auto, Realty and Capital Markets would lead the recovery.
Bear case, about 40% probability: Triggers are Brent moving back toward $108, the rupee slipping past ₹96, higher US yields or an RBI surprise. If the support covered in the technical section breaks, forced selling can follow. DIIs bought ₹33,455 crore in four sessions, and that capacity is not unlimited. Banks, Auto, Realty and Capital Markets would take the heaviest hit.
Invalidation: The bearish view weakens if FIIs turn net buyers and the resistance in the technical section is reclaimed on a closing basis. It strengthens if FII outflows stay above ₹5,000 crore a day.
Our Nifty view for next week is simple: stay patient, protect capital and wait for confirmation.
Key Events to Watch Next Week
| Event | Date | Forecast | Previous |
|---|---|---|---|
| US ISM Non Manufacturing PMI (Sep) | 5 Oct | 52.0 | 51.5 |
| Japan Average Cash Earnings YoY (Aug) | 6 Oct | 4.7% | 4.2% |
| RBI Interest Rate Decision | 7 Oct | 5.50% | 5.25% |
| Eurozone Retail Sales MoM (Aug) | 7 Oct | 0.2% | 0.1% |
| India Foreign Exchange Reserves | 9 Oct | $710 Billion | $704 Billion |
IPO Tracker This Week
| Company | M.Cap (Cr) | P/E | ROCE | Subscription |
|---|---|---|---|---|
| Vishal Nirmiti Limited | ₹581 | 23.8 | 29 | 0.6xx |
| Acme India Industries Limited | ₹460 | 20.3 | 27 | 1.9xx |
| Nityas Gems & Jewellery Limited | ₹432 | 19.0 | 43 | 0.7xx |
| Dove Soft Limited | ₹271 | 11.7 | 37 | 0.9xx |
| EverestIMS Technologies Limited | ₹184 | 14.0 | 33 | 1.7xx |