
This Indian Market Weekly Wrap covers 14 to 18 September 2026, a week that pushed Nifty 50 into its 7th straight red weekly candle.
Nifty closed at 23,346.40, down 0.22% for the week, after moving between 23,592.85 and 23,116.10. The weekly decline looks small, but the broader structure remains weak. Nifty is still firmly inside the downtrend that began in January 2026. The key technical levels and what they mean for next week are covered in the technical section below.
The biggest trigger this week was the US Federal Reserve. Chair Kevin Warsh delivered a 25 basis point hike, the first in three years, citing a strong jobs market, sticky inflation and the energy shock from the ongoing Iran war. The move strengthened the dollar, which reached a 7 week high, while the rupee slipped toward a record low near 96.
FIIs sold ₹7,620 crore during the week, extending the selling trend that has defined 2026. DIIs bought ₹11,232 crore and absorbed much of the pressure, preventing a deeper fall in Nifty. For now, the Indian stock market remains a sell on rise market until Nifty shows a clear structural reversal.
Key Takeaways:
• Nifty closed its 7th straight red week, keeping the January 2026 downtrend intact.
• FIIs sold ₹7,620 crore as the Fed hike strengthened the dollar and pressured the rupee.
• DIIs bought ₹11,232 crore, cushioning the fall but not changing the broader market structure.
• Key support, resistance and momentum levels are covered in the technical analysis section.
• Media and Metal led sector gains, while Defence fell 3.83% on profit booking.
Indian Market Weekly Wrap: Nifty Extends Downtrend Below 24,800 Resistance
Nifty 50 closed the week at 23,346.40, down 0.22%, marking its 7th straight red weekly close. The index opened at 23,576.15, touched a high of 23,592.85 and fell to 23,116.10 before recovering into Friday.
Nifty has now gone seven weeks without a meaningful weekly gain and is down nearly 7% from its August high. The weakness is being driven more by global flows than domestic factors. The Fed's rate hike this week strengthened the dollar and triggered further FII selling, putting additional pressure on Nifty.
The recovery from the weekly low was also narrow. Media and Metal led the bounce, while Defence remained under pressure due to sector specific profit booking. This narrow, macro driven recovery shows that FII flows continue to have a major influence on price action.
Indian Market Weekly Wrap: Bank Nifty Holds Up Better Than Nifty, But Not by Much
As per NSE India, Bank Nifty fell 0.44% this week to close at 56,358.70. It opened at 56,884.25, dropped to 55,794.75 on Tuesday and recovered into Friday.
The decline was smaller than Nifty's, continuing a pattern seen through this downtrend. Banking remains a relative outperformer, but it is still moving within the broader bearish trend. The most important data point for the Bank Nifty outlook is Max Pain at 57,200. That is more than 800 points above Friday's close, creating a relatively wide gap ahead of the 22 September expiry. This could support an expiry move toward 57,200 if Bank Nifty holds current levels.
PCR at 0.96 remains close to neutral, showing neither strong bullish nor bearish positioning. Max Call OI is concentrated at 58,000, while Max Put OI sits at 57,500. This gives Bank Nifty a wider trading range compared with Nifty. The broader trend remains unchanged. Bank Nifty is still below its recent highs, while a stronger dollar, weaker rupee and continued FII selling remain headwinds for banking stocks.
Relative strength does not mean a trend reversal. The key level is 57,500. A close above it could open the path toward 58,000 into expiry. A break below 55,800 would weaken the setup and bring Bank Nifty back in line with the broader market's weakness.
Indian Market Weekly Wrap: Media and Metal Lead as Defence Drops 3.83%
Sector performance in this Indian Market Weekly Wrap was mixed, with no clear sector rotation. Media gained 1.08%, followed by Metal at 0.41% and Oil & Gas at 0.11%. Financial Services, IT, Energy, Realty and Auto fell between 0.14% and 0.64%.
Defence was the clear outlier, falling 3.83%. The decline came mainly from profit booking after the sector's strong rally following nearly ₹1.10 lakh crore of procurement approvals by the Defence Acquisition Council.
Media's gain also looks more like a bounce in a beaten down sector than a broader shift in sentiment. The narrow declines across IT, Financial Services and Auto suggest macro flows, rather than sector specific factors, continue driving the Indian stock market.
What matters next is whether Defence stabilises after the current profit booking.
Indian Market Weekly Wrap: FII Selling Impact on Indian Market Traces Back to the Fed
FIIs sold ₹7,620 crore in the cash segment this week, while DIIs bought ₹11,232 crore. DII buying absorbed most of the foreign selling, helping limit Nifty's decline to just 0.22%.
The main trigger was the US Federal Reserve. On 16 September, the Fed raised rates by 25 basis points to 3.75% to 4.00%, its first hike in three years. The move strengthened the dollar, with the Dollar Index reaching a 7 week high near 100.45. A stronger dollar makes US assets more attractive and puts pressure on emerging markets like India. The rupee tested 96 against the dollar before closing near 95.89.
The problem is amplified by crude oil. Elevated crude increases India's import bill and dollar demand, putting further pressure on the rupee. At the same time, rupee depreciation reduces the dollar returns FIIs earn from Indian equities, creating another reason to reduce exposure. The FII selling pattern also remains important. Selling peaked at ₹3,209 crore on Thursday after the Fed decision, followed by a ₹600 crore inflow on Friday. One positive session does not change the broader outflow trend.
For now, DII buying remains the biggest support for the Indian stock market. What matters next is the dollar and crude. Further dollar strength could keep FII selling elevated, while a cooling in crude could ease pressure on the rupee and slow foreign outflows.
Indian Market Weekly Wrap: F&O Data Points to a Range Ahead of Expiry
The F&O setup in this Indian Market Weekly Wrap points to a range bound expiry for both Nifty and Bank Nifty.
Nifty's Max Pain at 23,350 is almost exactly at Friday's close, while Max Call OI at 24,000 remains the key resistance. Bank Nifty has a wider setup. Max Pain sits at 57,200, around 842 points above Friday's close. Its PCR of 0.96 is also more neutral compared with Nifty's 1.13.
India VIX fell 7.36% on Friday to 11.39. Falling volatility during a weak week suggests traders are expecting a controlled expiry rather than a sharp move.
The base case remains a range of 23,300 to 23,700 for Nifty and 56,000 to 57,500 for Bank Nifty. The upside trigger is unwinding of Nifty's 24,000 Call OI. The downside trigger is a break below 23,300 in Nifty and 55,800 in Bank Nifty.
For now, the F&O setup supports consolidation rather than a breakout.
IPO Tracker This Week
| Company | M.Cap (Cr) | P/E | ROCE | Subscription |
|---|---|---|---|---|
| National Stock Exchange of India Ltd. | ₹441787.50 | 35.40 | 42.80 | 1.15xx |
| Sonaselection India Ltd. | ₹562.60 | 16.53 | 19.69 | 0.49xx |
| Varmora Granito Ltd. | ₹3344.97 | 60.66 | 9.89 | 0.00xx |
| Hero Motors Ltd. | ₹1000.00 | N/A | N/A | 7.01xx |
Key Events to Watch Next Week
| Event | Date | Forecast | Previous |
|---|---|---|---|
| IN: HSBC Flash Manufacturing PMI | 23-Sep-2026 | 56.4 | 56.7 |
| IN: HSBC Flash Services PMI | 23-Sep-2026 | 58.1 | 58.5 |
| US: S&P Global Flash Manufacturing PMI | 23-Sep-2026 | 53.2 | 53.9 |
| US: S&P Global Flash Services PMI | 23-Sep-2026 | 55.8 | 56.5 |
| US: Initial Jobless Claims | 24-Sep-2026 | 204K | 196K |
Indian Market Weekly Wrap: Fed Hike, Iran War and Rupee Drive the Week
US Federal Reserve Delivers First Rate Hike in Three Years
The Fed raised rates by 25 basis points to 3.75% to 4.00% on 16 September, its first hike since July 2023. The move strengthened the Dollar Index to a 7 week high near 100.45, putting further pressure on the rupee and FII flows into Indian equities.
Rupee Tests Record Low Near RBI's 96 Defence Line
The rupee fell toward 96 against the dollar before closing near 95.89. RBI intervention slowed the decline, but elevated crude and a wider current account deficit continue to pressure the currency. A weaker rupee also reduces dollar returns for FIIs, adding to selling pressure in Indian equities.
Defence Stocks Correct Sharply After Sector Rally
India Defence fell 3.83%, the week's biggest sector decline. The correction followed profit booking after the Defence Acquisition Council cleared nearly ₹1.10 lakh crore of procurement proposals on 8 September. Selling increased after Solar Industries announced its ₹12,951 crore acquisition of Omnia Holdings. The move reflects profit booking after a strong rally rather than a change in the defence order pipeline.
Indian Market Weekly Wrap: Technical View
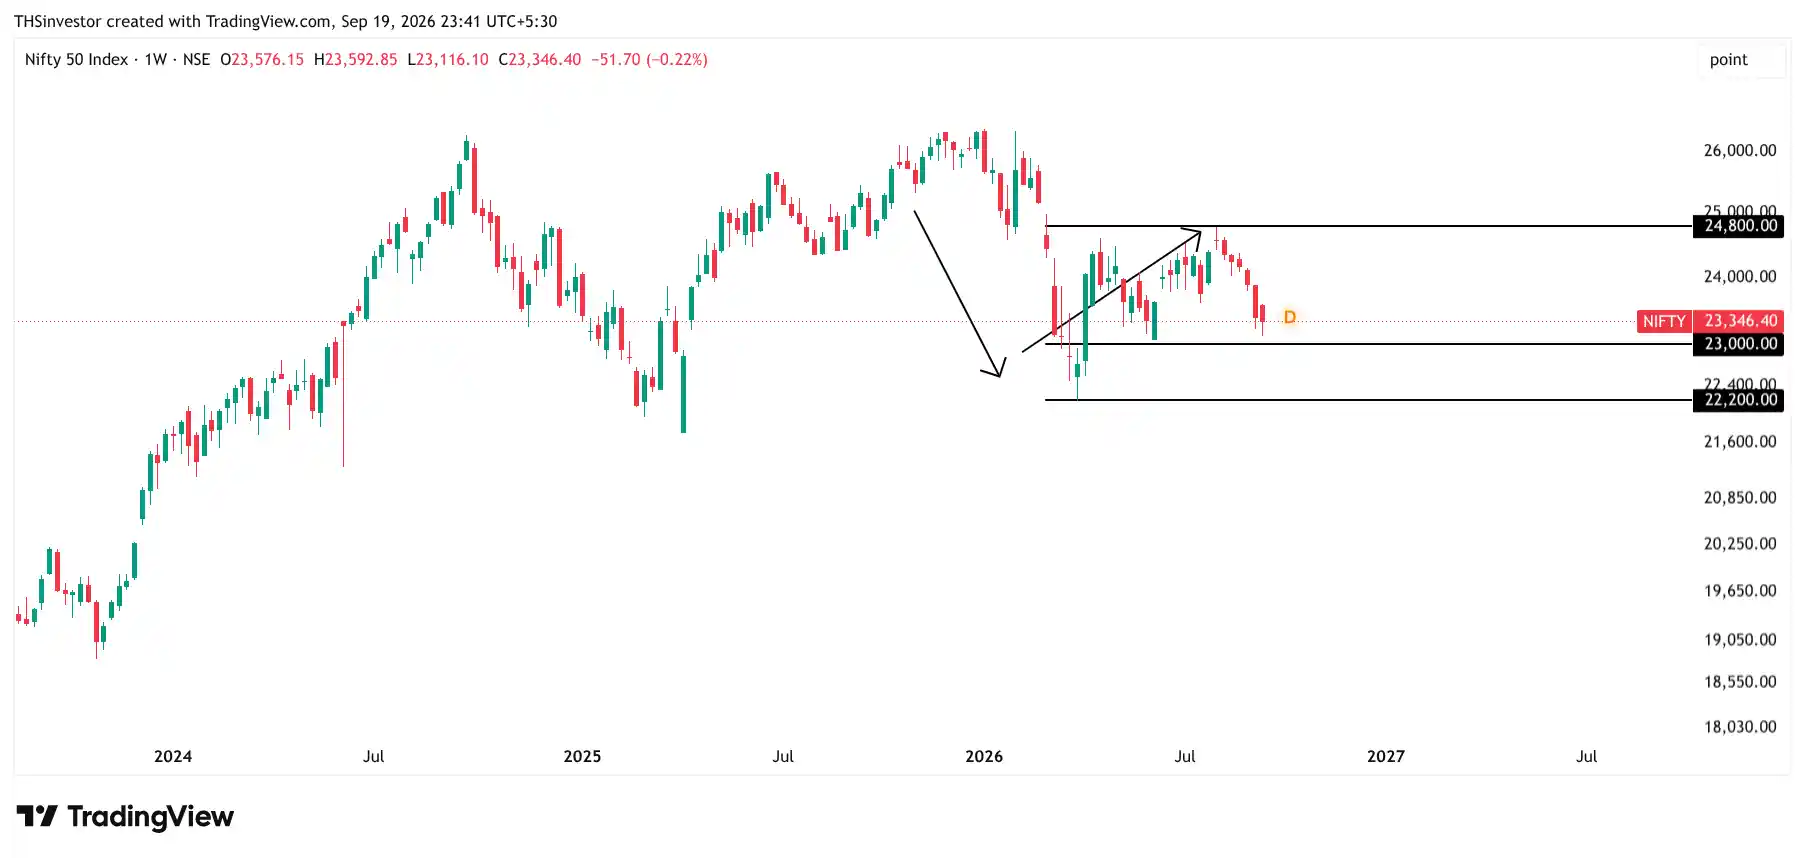
Trend: Seven consecutive red weeks show sellers continue to control rallies. Buyers have not managed a meaningful recovery during this decline.
Resistance: 24,800 is the key level. Until Nifty closes above it with strength, rallies remain selling opportunities rather than a trend reversal.
Support: 23,000 is the first major support, followed by 22,200. A break below 23,000 opens the path toward the March 2026 low near 22,200.
Momentum: Daily RSI is oversold. This increases the possibility of a short term bounce, but does not confirm a trend reversal. The weak daily candles still keep the bias bearish.
Near Term Setup: Nifty formed a small lower wick near 23,116, showing some buying interest. Oversold RSI also supports a possible bounce toward 23,700, near the daily 21 EMA. However, the broader trend remains bearish below 24,800.
Bias: Sell on rise. Recoveries remain potential exit points until Nifty reclaims 24,800 with strong volume.
Invalidation: A weekly close above 24,800 would weaken the bearish setup. A weekly close below 23,000 would confirm further downside toward 22,200.
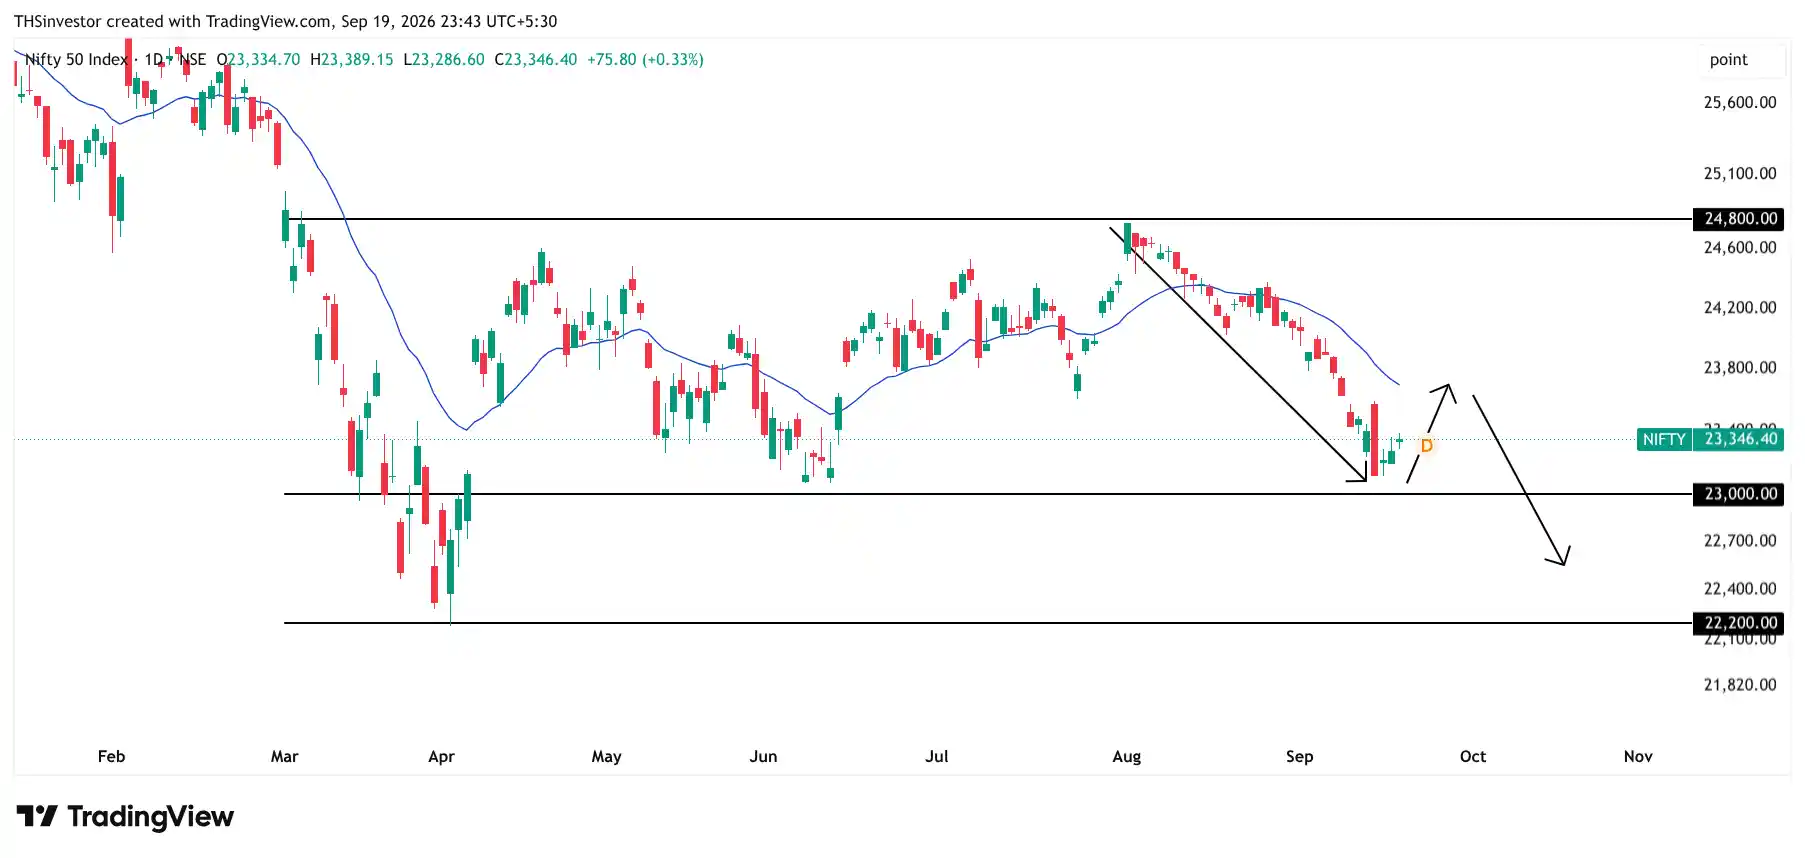
Indian Market Weekly Wrap: Bull Case, Bear Case and What Comes Next
The base case for this Indian Market Weekly Wrap remains a continuation of the downtrend that began in January 2026. Seven consecutive red weekly candles and the Fed's hawkish shift continue to favour sellers, although a short term bounce remains possible.
Bull case: Crude cools as the Iran conflict shows signs of de escalation and the rupee stabilises below 96. This could slow FII selling and give Nifty room to reclaim the key resistance highlighted in the technical section.
Bear case: Crude stays elevated, the dollar strengthens on expectations of further Fed hikes, and FIIs continue selling into rallies. A break of the key support levels would confirm that the downtrend still has further room.
The biggest swing factor remains the Fed. Further tightening would keep the dollar strong and FII outflows active. A pause would reduce pressure on the rupee and create a better setup for Indian equities. Domestically, elevated crude continues limiting the RBI's room to act. This makes upcoming RBI commentary and rupee movement important for the Indian stock market.
DII buying should continue absorbing FII supply, but so far it has supported prices rather than changed the broader trend. For now, the market remains range bound in the short term. The key question is whether Nifty can reclaim resistance or breaks support as macro conditions evolve.