
Nifty had a massive week, gaining 8.39% to close at 24,986.40 after Sunday's Muhurat session. Friday's regular close came in at 25,030.35, taking the gain to 8.58%. Only 10 weeks since 2000 have seen a bigger gain.
Last week, we said a trend reversal would need a strong weekly close above 23,200. Nifty closed 1,786 points above that level. We stayed cautious while the market rallied but the condition we were waiting for was met comfortably.
FIIs bought ₹45,960.02 crore during the week. Banks joined the rally and market breadth improved from 0.28x to 2.31x.
Key Takeaways:
- FIIs bought on all five sessions. This looks like a return of foreign money into India rather than a one-day trade.
- DIIs sold on every up day and absorbed more than half of FII buying. This domestic selling could slow the rally.
- Banks and broader market participation joined the move. This is no longer a rally driven by just a few heavyweight stocks.
- VIX rose to 18.43 despite the rally. Traders are still buying protection and the risk of a sharp pullback hasn't gone away.
Nifty Analysis for Next Week: Nifty Jumps 8.39%
Nifty opened the week at 23,053 and closed at 24,986.40, gaining 8.39%. The weekly range was 1,924 points (23,207.05-25,131.20) against 731 points last week. That's 2.6 times wider. When ranges expand this sharply, it usually means sellers are struggling to defend their levels.
Look at how the rally played out. Monday gained 1.68%, Tuesday 1.58%, Wednesday 0.63%, Thursday 2.40% and Friday 2.01%. Every session closed green. This wasn't a one-day spike. Buyers showed up throughout the week.
Historically, this is rare. Of the 11 biggest weekly gains since 2000, including this one, only three had five consecutive green sessions: February 2000, February 2021 and now. Even the biggest weekly gain of 15.44% in May 2009 was largely driven by a single 17.74% session. This rally was different. It was steady buying across the week and that's much harder to fade.
The trigger came from global markets. Crude fell and Asian tech stocks took a beating. Foreign money started looking beyond chip stocks and India became a major destination.
For Nifty Analysis for Next Week, Monday's price action will be important. A shallow dip followed by buying would show that demand is still intact.
Nifty Analysis for Next Week: Bank Nifty Adds 7.61%
Bank Nifty opened at 54,686 and closed at 58,850.65, gaining 7.61%. The weekly range was 4,658 points (54,582-59,240.50). Last week, banks captured only about a third of Nifty's gain. This week they came within 0.78 percentage points of it.
Last week, we said banks needed to break above 55,068.50 before we could trust the recovery. They closed above that level on Tuesday at 55,540.05. That was the first sign that banks were joining the rally and it wasn't just a few heavyweight stocks pulling the market higher.
Banks are among the biggest and most liquid stocks in foreign portfolios. So when foreign money returns to India, they are usually among the first to benefit.
But this also tells us what is driving the rally. The concerns around credit growth haven't gone away. This is largely a flow-driven move rather than a fundamental improvement in the banking sector. If foreign flows reverse, banks could be among the first to take a hit.
For Nifty Analysis for Next Week, Bank Nifty remains our confirmation index. Banks have held their gains and participation has improved. If they start breaking down first during a pullback, Nifty could follow.
Nifty Analysis for Next Week: News That Moved the Market
FIIs Buy ₹45,960 Crore in Five Sessions and Reverse October's Selling
Foreign investors reversed October's selling with ₹45,960.02 crore of net cash buying across five straight sessions. Thursday's ₹14,974.68 crore was the largest single day of foreign buying in over a year and it landed heavily on large cap banks and financials. Those are the heaviest index weights, so a flow that size moves the index fast. That is how a flow story became an 8% week.
US Midterms and AI Regulation Fears Crush Global Tech as Kospi Falls Over 8%
The Democratic Party's midterm win raised fears of tighter AI regulation and slower data centre spending. Global chip and tech stocks sold off hard, with South Korea's Kospi down over 8% and Japan's Nikkei down 5% to 6%. India has little exposure to the AI hardware cycle, so funds leaving Korea and Japan rotated into Indian financials and consumption. That is why India rose while Asia fell. But India is not immune. If this selloff turns into broad risk aversion, funds sell whatever is liquid to raise cash, as they did when even gold and silver were dumped last Friday.
Brent Pulls Back From Near $118 as West Asia Peace Talks Revive
Renewed diplomatic talks eased supply fears and pulled Brent crude down from six month highs near $118 a barrel. Lower crude helps India three ways: a smaller import bill, a softer inflation outlook and a firmer rupee. That is why Oil & Gas, Auto and Realty jumped.
Nifty Analysis for Next Week: FIIs Buy ₹45,960 Crore
FIIs bought ₹45,960.02 crore in the cash market this week. They weren't waiting for dips. They were buying at higher levels.
Last week, we questioned whether FIIs would continue buying on days when the market actually moved higher. They did, on all five sessions. That answers our biggest doubt. Thursday also saw the highest single-day FII buying in over a year.
DIIs sold ₹24,196.52 crore, a sharp reversal from ₹3,109.79 crore of buying last week and ₹10,942.19 crore the week before. They sold on all five sessions, including ₹10,444.54 crore on Thursday. That's nearly 70% of the day's FII buying.
This explains why the market had to move so sharply. Foreign buyers kept bidding higher to absorb the supply coming from domestic institutions.
For Nifty Analysis for Next Week, the key question is whether FIIs continue buying on red days. If they buy the dips, the rally has strong support. If buying stops at the first sign of weakness, this could turn out to be a short-covering rally.
Nifty Analysis for Next Week: Capital Markets Leads at 11.33%
Capital Markets (+11.33%), Financial Services (+9.99%) and Oil & Gas (+9.74%) led the rally.
Capital Markets benefited from the return of foreign money as brokers, exchanges and fund houses gain from higher volumes and stronger flows. The sector has now recovered all the ground it was missing last week.
Oil & Gas went from last week's only losing sector to the third-best performer as falling crude eased margin pressure. Auto (+9.52%) and Realty (+9.45%) also rallied as lower crude eased inflation concerns.
IT gained just 0.81%, making it the worst performer. Despite the global tech sell-off, money leaving Asian AI trades moved into Indian banks and cyclicals rather than IT. Media and Defence also lost ground in the sector rankings. Leadership is rotating quickly.
Breadth confirms the broader rally. Nifty 500 recorded 344 advances against 149 declines, taking the advance-decline ratio to 2.31x from 0.28x last week.
Nifty Analysis for Next Week: Nifty Option Chain Analysis
Nifty's biggest battle is at 25,000. Both Call and Put OI are highest at this strike while Nifty closed at 24,986.40, just 14 points below it.
This makes 25,000 a key battleground. Call writers are defending it as resistance while Put writers are trying to hold it as support. A decisive break either way could trigger aggressive hedging and sharp moves.
Nifty PCR fell to 1.28 from 1.59, showing that the earlier put-heavy positioning has eased. Writers are becoming more cautious about upside beyond 25,000. Max Pain stands at 24,000, nearly 986 points below the close. With monthly expiry on 23 November, its influence is limited for now but could increase as expiry approaches.
India VIX jumped 20% to 18.43 from 15.30 despite the massive rally. Traders are still buying protection against a reversal. CPI data on 12 November adds another reason for caution.
You can track live OI changes on the NSE India website.
Nifty Analysis for Next Week: Nifty Technical Analysis
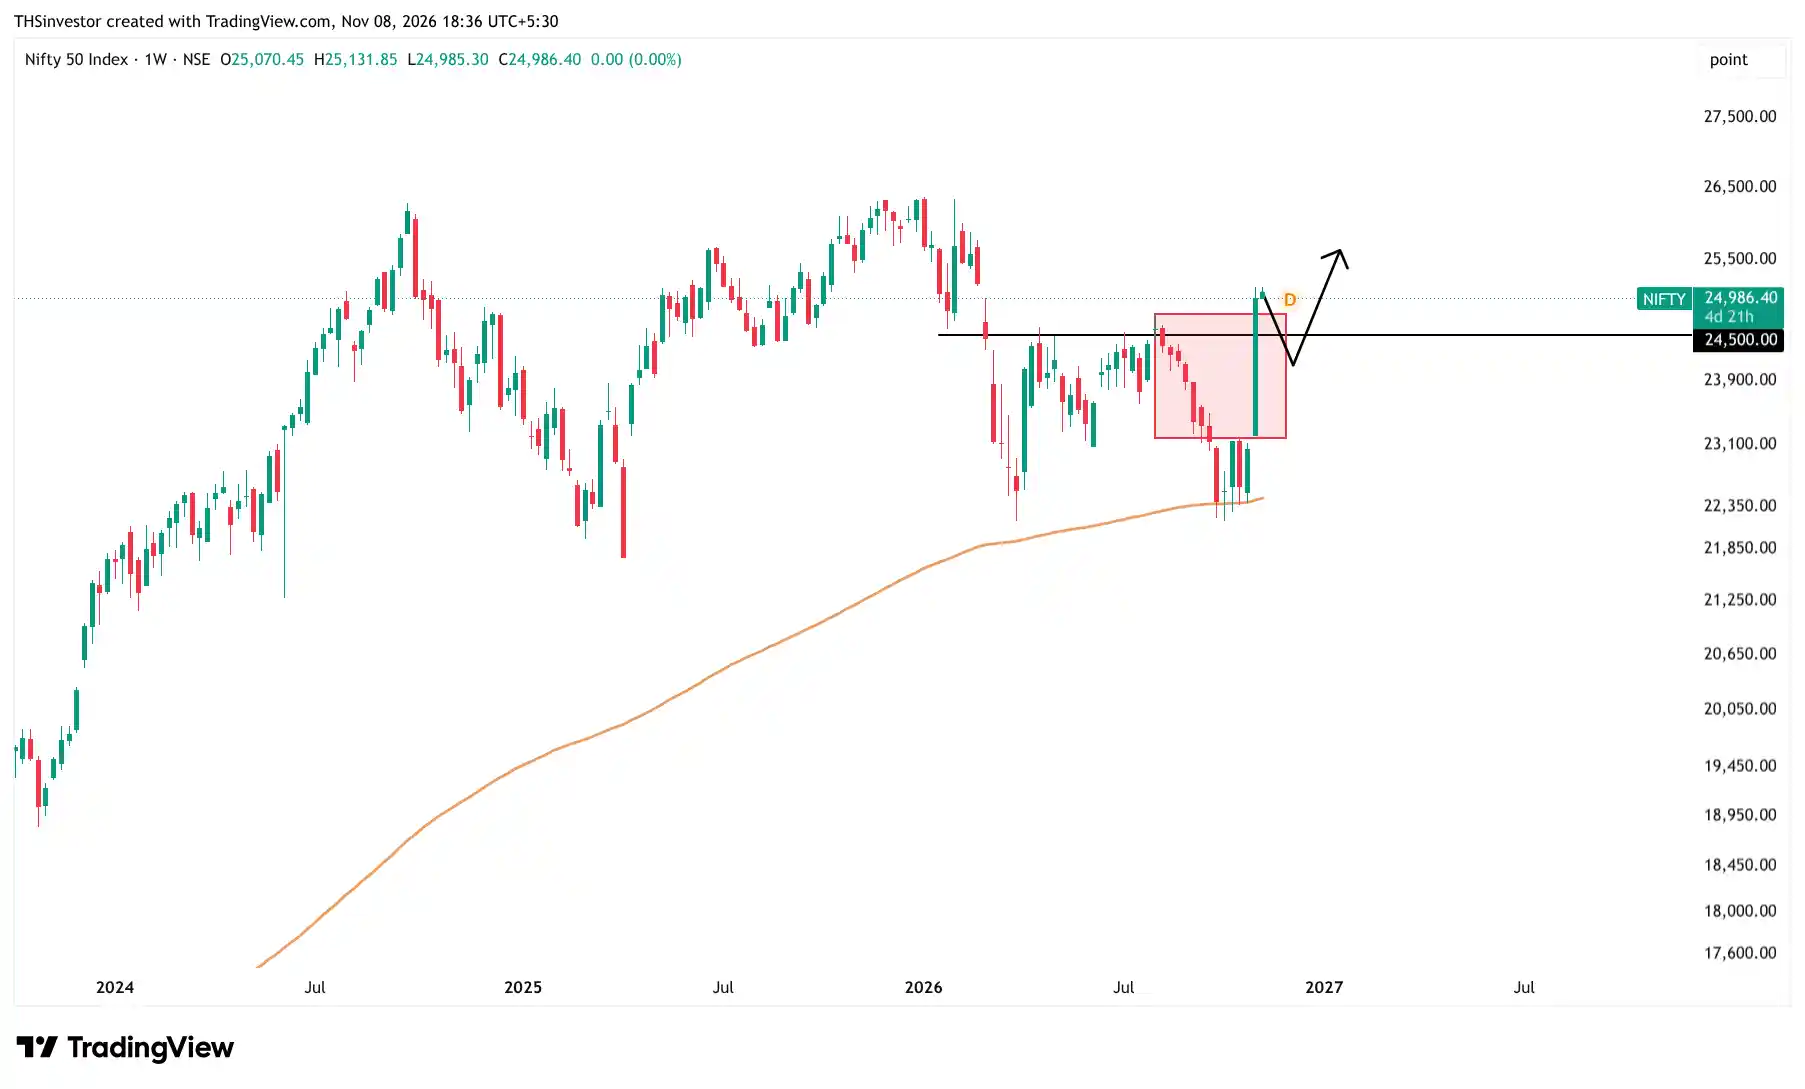
There is no major resistance until the all-time high. At this pace, we could see that level sooner than expected. This week's high of 25,131.20 is the only immediate hurdle.
Our weekly bias remains bullish with 24,500 as the key support. A break below it could push Nifty back into a sideways phase. Also, don't rush to turn bearish on the first dip below support. A quick wick below 24,500 could trigger stop losses before the market moves higher again.
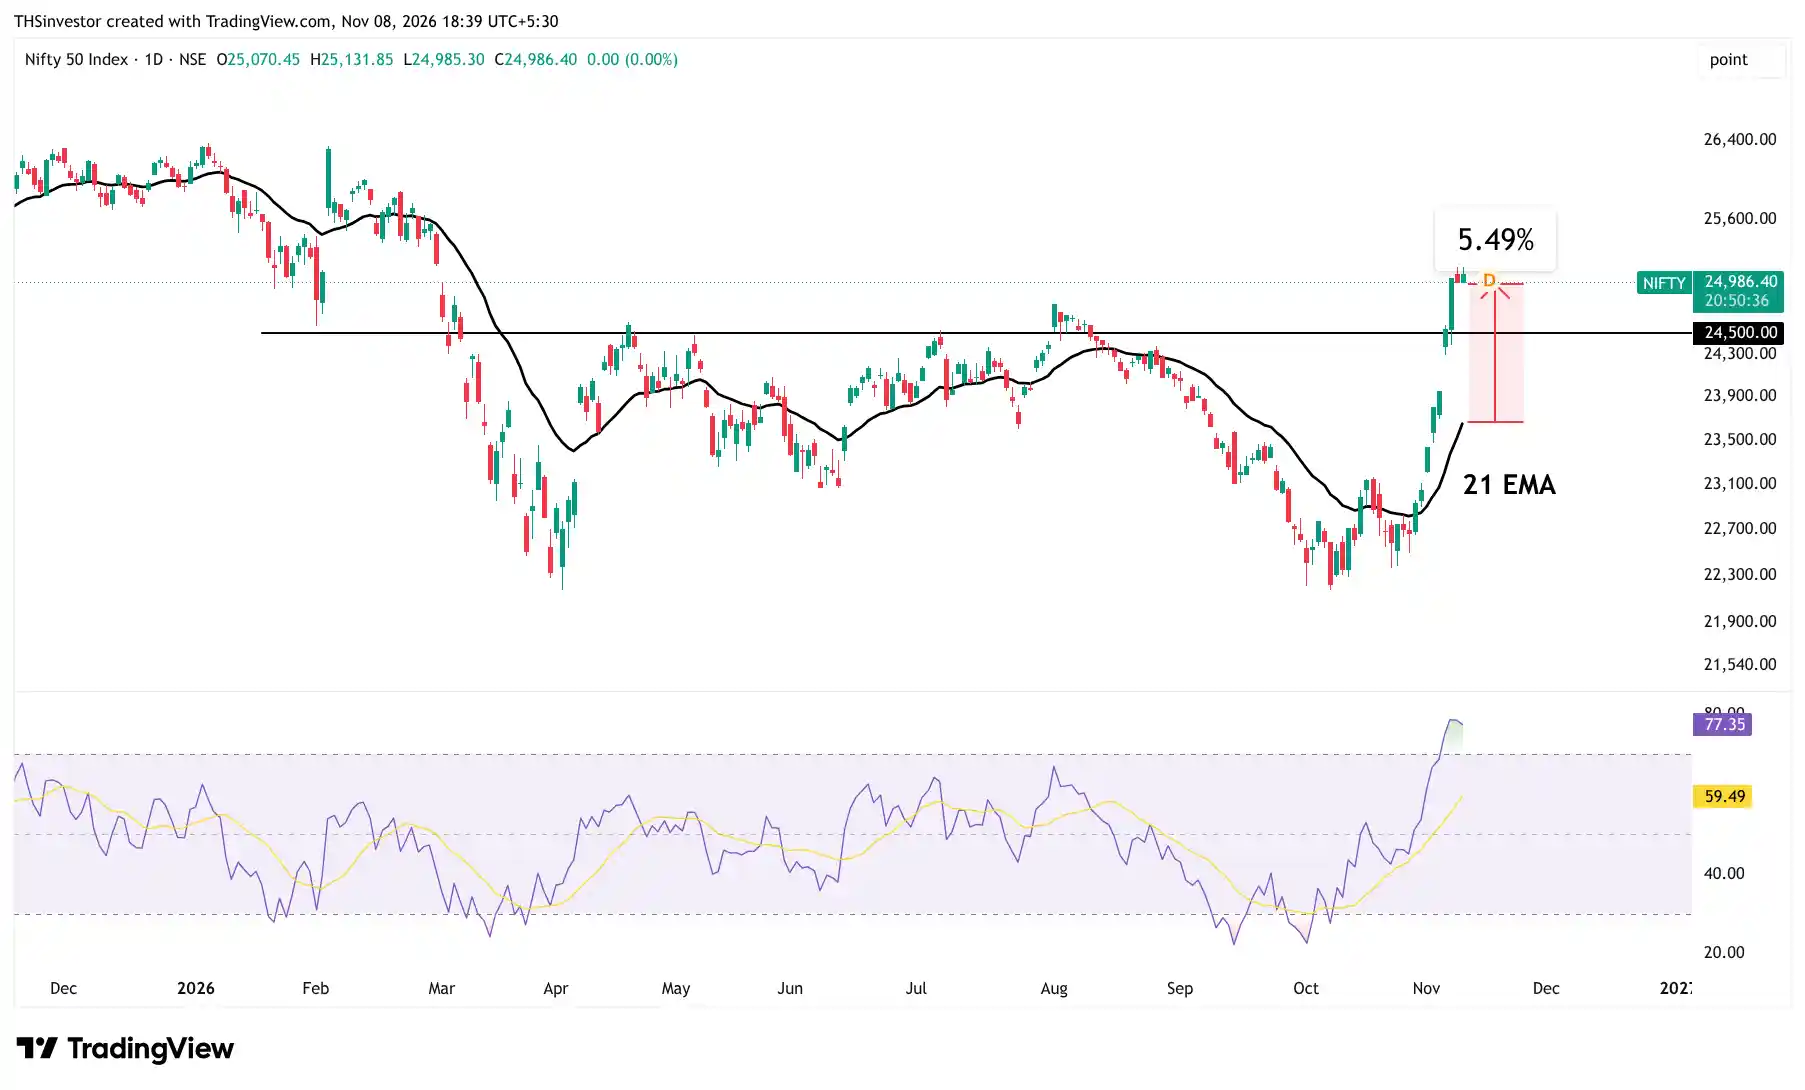
The daily chart, however, looks stretched. RSI is approaching overbought territory and Nifty is trading well above its 21 EMA after seven consecutive green sessions. The gap between price and the 21 EMA suggests the market needs a breather.
This rally ranks third among 52 streaks of seven or more consecutive green sessions since 2000. A pullback wouldn't be surprising.
The approach for next week is simple: Stay bullish but don't chase. Let the market retrace and look for buying opportunities.
Nifty Analysis for Next Week: Stay with Trend
Our view remains bullish, but we expect a pause before the next leg higher. The weekly trend has turned positive but the sharp rally suggests some consolidation or a pullback first.
FII buying has been strong, with purchases across all five sessions. But DIIs sold into every up day, both indices closed below their highs and VIX climbed to 18.43 despite the rally.
Dips should attract buyers but chasing the market here doesn't make sense.
Historically, only 10 weeks since 2000 have recorded a bigger gain than this one. Nifty was higher a week later in 8 of those 10 cases and a month later in 7. Big rallies after prolonged downtrends have also delivered some of the strongest one-year returns. The sample is small, so treat this as context rather than a forecast.
The biggest risk is that this rally turns out to be a short-covering burst rather than the start of a sustained uptrend. If FII buying dries up while DIIs continue selling, the market could struggle to find buyers. A sharp recovery in crude or a broader global tech sell-off could also trigger fresh selling.
A break below the key support discussed in the technical analysis, along with FII selling on a down day, would be an early warning that the trend is weakening.
Our view for next week remains bullish. Expect some consolidation, let the market pull back and look for long opportunities rather than chasing prices at higher levels.
Key Events to Watch Next Week
| Event | Date | Forecast | Previous |
|---|---|---|---|
| MSCI Index Review Announcement | 11 Nov | ||
| CPI Inflation | 12 Nov | 5.54 | |
| WPI Inflation | 16 Nov | 11.39 | |
| PPI Inflation | 16 Nov | 11.39 | |
| Core Sector | 20 Nov | 7.94 | |
| Real GDP | 30 Nov | 7.8 |